Home Equity Loans – Lines of Credit

Use What You’ve Built, Without 
Leaving Home.

Our home equity loans and home equity lines of credit (HELOC) are a great way to use the value of your home to make home improvements, cover unexpected expenses, consolidate debt, or pay for a large expense like college tuition or a new car.

Home Equity Line of Credit (HELOC)

Qualified borrowers may receive rates as low as

6.75%

APR*

*See rate details →
Variable APR (Annual Percentage Rate) based on the Prime Rate as published in the Wall Street Journal (currently 7.00%). Rate is as of 09/17/2026. Rates are subject to change. Maximum APR is 18.00%. An initial draw of $25,000 is required to be made at closing and remain outstanding for 90-days. The initial draw excludes any payoff to an existing loan with Reading Cooperative Bank. Interest only payments for initial 10 years, with an additional 15 year payback of principal & interest. Maximum LTV is 80%. Rate and terms may vary based upon credit history. Not available for homes currently for sale or intended to be sold. Subject to credit approval. 1-4 family, owner occupied primary residences, and condominiums qualify. Property insurance required. Flood insurance may be required. Consult a tax advisor for information regarding the deductibility of interest and charges. To open, maintain and discharge a line of credit, you may have to pay certain fees. These fees generally total between $0 and $750.00. During the life of the program, you will be assessed an annual fee of $50.00 on the last business day of the billing cycle, following the anniversary date of the loan. An early termination fee of $500.00 applies for lines closed within thirty-six (36) months from date of closing.For loan amounts up to $100,000, your debt-to-income ratio cannot exceed 45%, and you will need a minimum mid Fico Score of 620.For loan amounts more than $100,000 and up to $250,000, your debt-to-income ratio cannot exceed 40%, and you will need a minimum mid Fico Score of 680.Depending on your loan to value, debit to income ratio, and credit score, you may qualify for a higher loan amount. Please speak to a loan officer for more details.

Discounted Fixed Rate Home Equity Loan

Qualified borrowers may receive rates as low as

6.032%

APR*

*See rate details →
APR (Annual Percentage Rate) is the annual rate that is charged for borrowing, expressed as a single percentage number that represents the actual yearly costs of funds over the term of the loan. This includes any fees or additional costs associated with the transaction. Minimum payment does not include insurance and taxes, and the payment may be greater.For loan amounts up to $100,000, your debt-to-income ratio cannot exceed 45%, and you will need a minimum mid Fico Score of 620. CLTV cannot exceed 75%.For loan amounts more than $100,000 and up to $250,000, your debt-to-income ratio cannot exceed 40%, and you will need a minimum mid Fico Score of 680.Depending on your loan to value, debit to income ratio, and credit score, you may qualify for a higher loan amount. Please speak to a loan officer for more details.

How Does It Work?

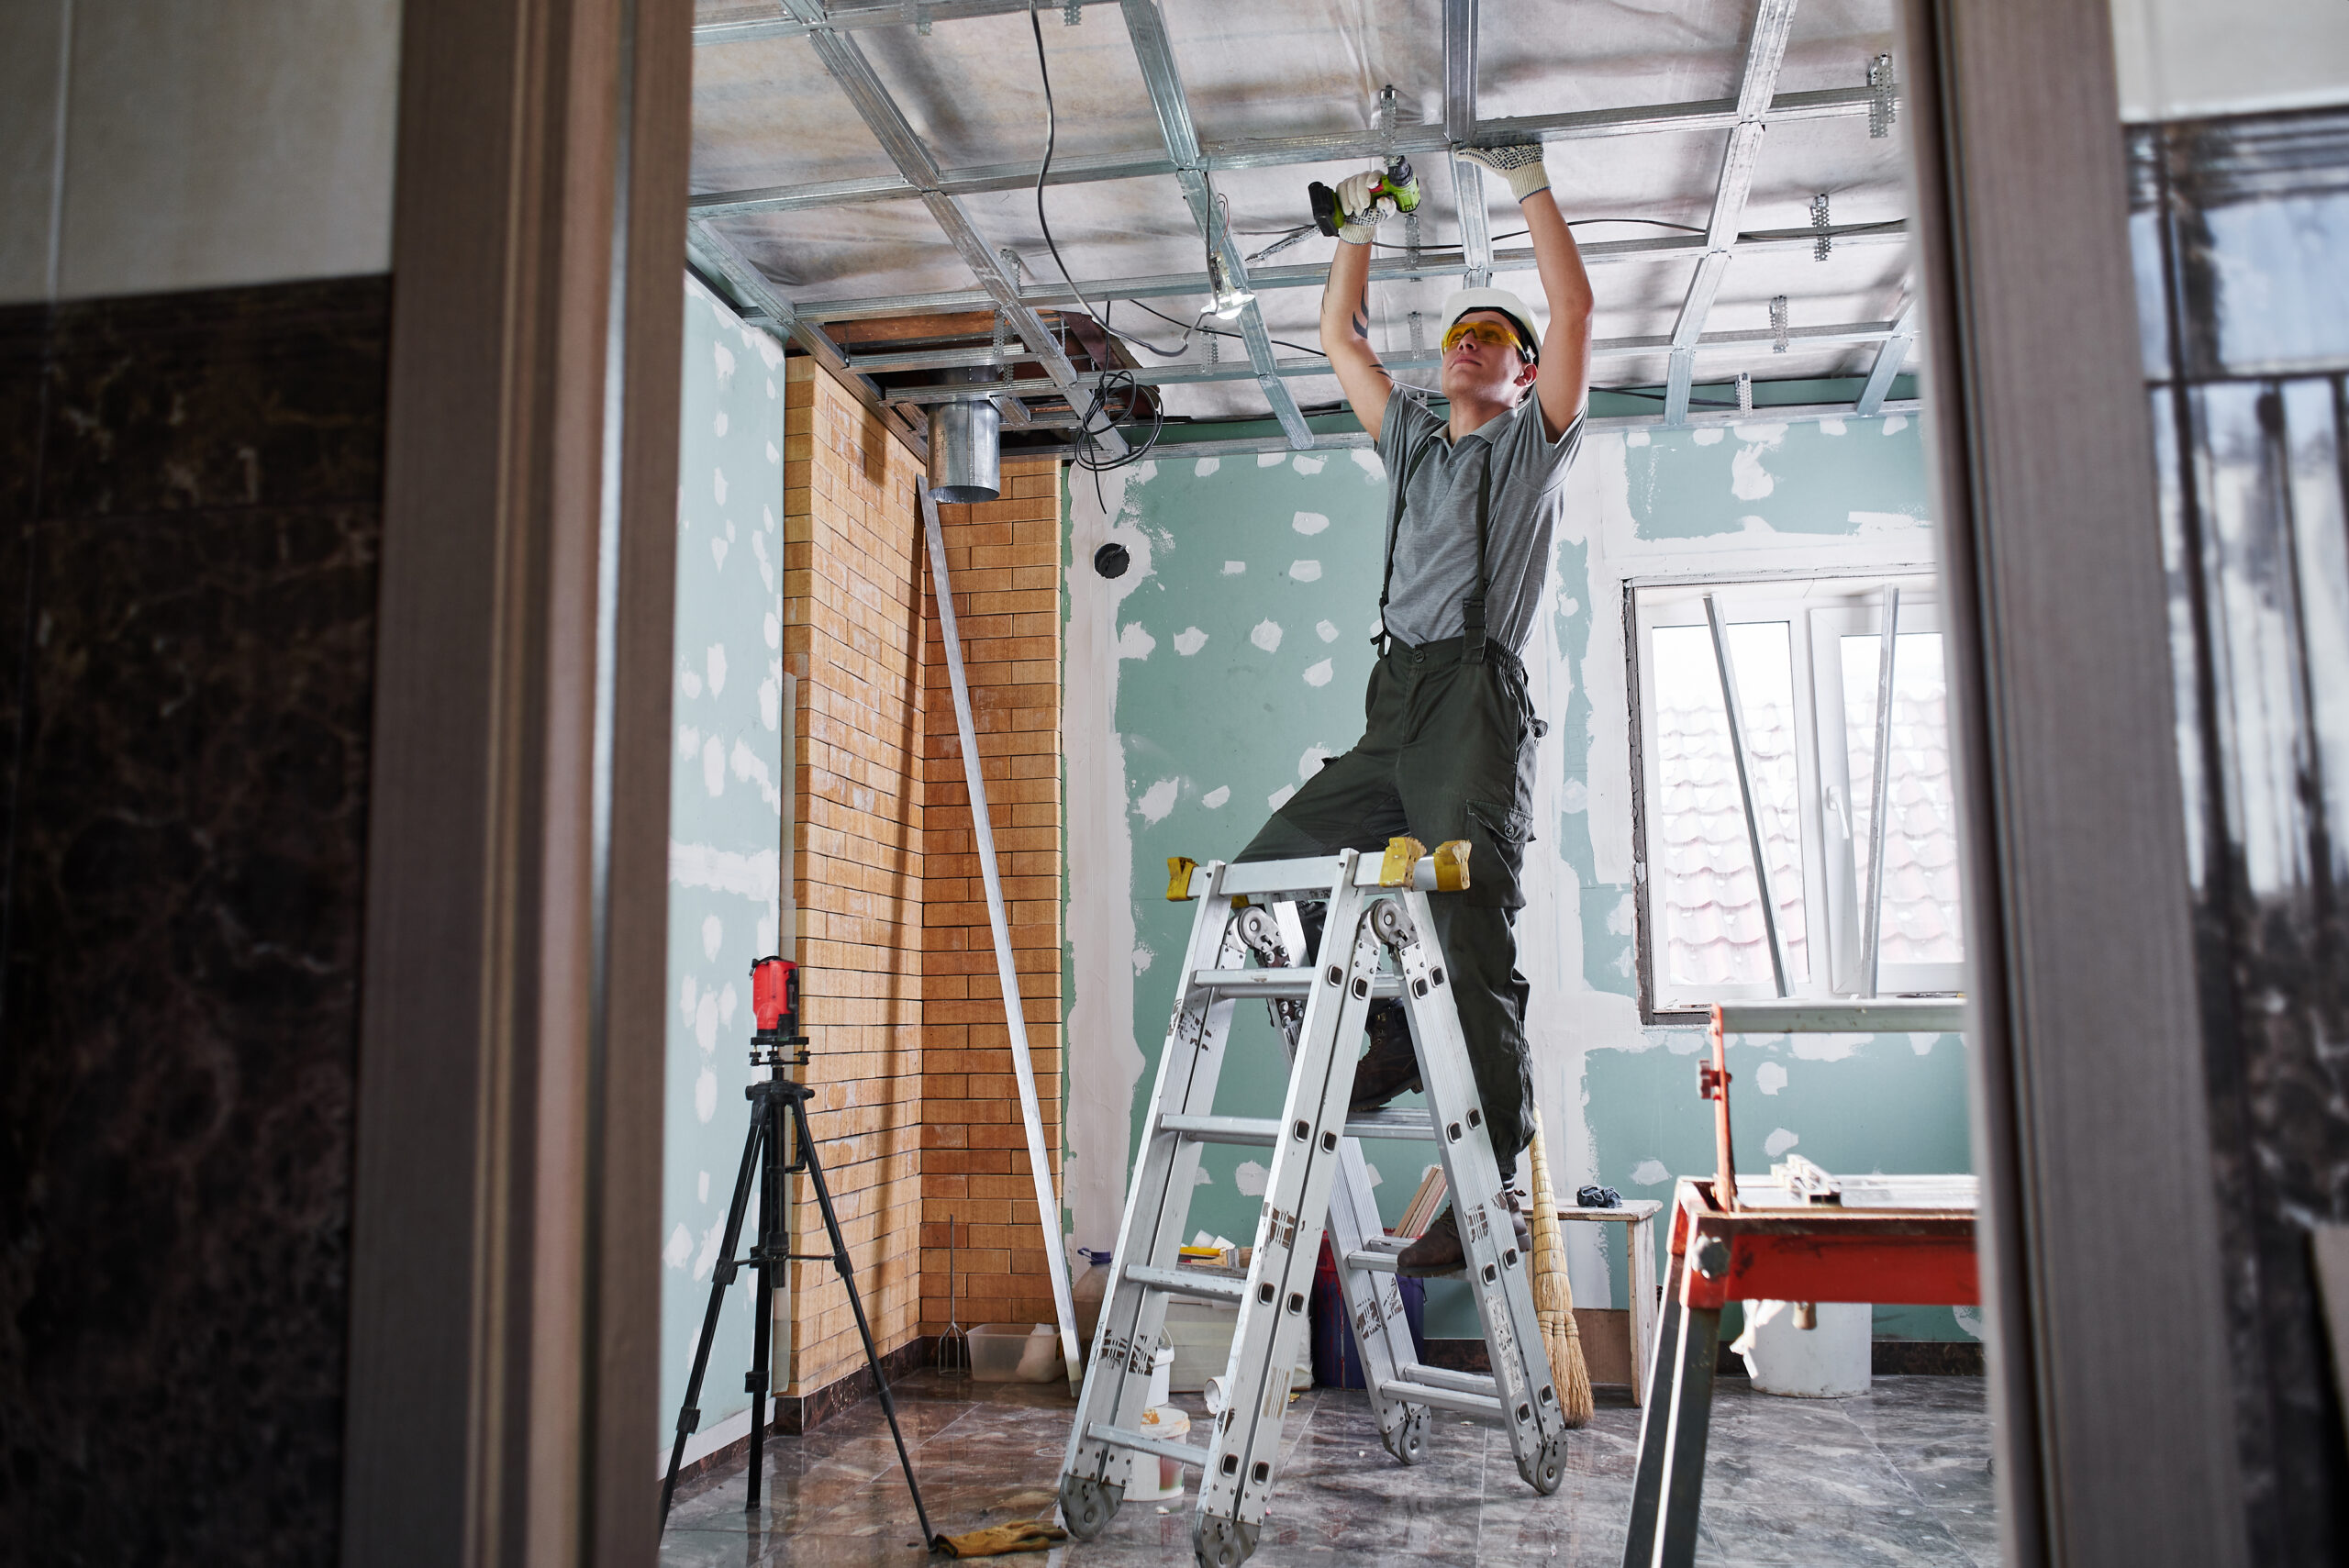
Room repair. Interior finish. young builder makes a plasterboard ceiling, standing on a stepladder

A HELOC gives you access to a revolving line of credit with the flexibility to meet needs as they arise. It involves two phases: (1) a draw period, during which you can borrow, repay, and borrow again; and (2) a repayment period, during which you can’t borrow anymore, and you must start repaying the principal plus interest.

Three Tips for Tapping Into
Your Home Equity.
Borrow Only What You Need

Your house secures the loan, 
treat a HELOC like a credit card with higher stakes.
Clipboard Icon

Plan for the Next Phase

After the draw period, the repayment period begins 
and both principal and 
interest are due, so your payment may increase.
Interest Icon

Know How the Interest Works

HELOCs have variable interest rates, so your monthly payment can go up or down as market rates change.


Home Equity Line of Credit (HELOC)7.00%1
Minimum loan amount is $25,000
Maximum loan amount is $250,0004
Maximum LTV (loan to value):
For loans up to $100,000, LTV cannot exceed 80%2
For Loans more than 100,000 and up to $250,000, LTV cannot exceed 75%3,410 Year Draw – 15 Year Repayment – 25 Year Term
 

1Variable APR (Annual Percentage Rate) based on the Prime Rate as published in the Wall Street Journal (currently 6.75%). Rate is as of 09/17/2026. Rates are subject to change. Maximum APR is 18.00%. An initial draw of $25,000 is required to be made at closing and remain outstanding for 90-days. The initial draw excludes any payoff to an existing loan with Reading Cooperative Bank. Interest only payments for initial 10 years, with an additional 15-year payback of principal & interest. Maximum LTV is 80%. Rate and terms may vary based upon credit history. Not available for homes currently for sale or intended to be sold. Subject to credit approval. 1-4 family, owner occupied primary residences, and condominiums qualify. Property insurance required. Flood insurance may be required. Consult a tax advisor for information regarding the deductibility of interest and charges. To open, maintain and discharge a line of credit, you may have to pay certain fees. These fees generally total between $0 and $750.00. During the life of the program, you will be assessed an annual fee of $50.00 on the last business day of the billing cycle, following the anniversary date of the loan. An early termination fee of $500.00 applies for lines closed within thirty-six (36) months from date of closing.
2For loan amounts up to $250,000, your debt-to-income ratio cannot exceed 45%, and you will need a minimum mid Fico Score of 620.
3For loan amounts more than $100,000 and up to $250,000, your debt-to-income ratio cannot exceed 40%, and you will need a minimum mid Fico Score of 680.
4Depending on your loan to value, debit to income ratio, and credit score, you may qualify for a higher loan amount. Please speak to a loan officer for more details.

Conversion to a Fixed Rate, Fixed Term – Conversion to fixed term options is available 90 days after closing. Prior to the Repayment Period, you may elect from time to time (but in no event more than two separate times) to convert all or part of the outstanding principal balance of your Equity Line to a fixed rate utilizing our “Fixed Rate, Fixed Term Option”. You may do so by delivering to us our Conversion Election Form signed by you in which you set forth the dollar amount of the converted portion, which in no event may be less than Ten Thousand Dollars ($10,000), the number of months between 60 – 240, in which you wish to repay the Converted Portion on a direct amortization basis and your election to convert all or a portion of your outstanding balance to a Converted Portion. Each “Fixed Rate, Fixed Term” would be evidenced by a separate “Fixed Rate, Fixed Term Option” Addendum, and your credit limit would be reduced by the original principal amount of each “Fixed Rate, Fixed Term Option”. Any principal repaid on the Installment Loans will increase the available credit for future advances. The maturity date of the “Fixed Rate, Fixed Term” would be established as of the date the “Fixed Rate, Fixed Term Option” Addendum is signed evidencing such change, provided however, that in no event shall the maturity date of the Addendum exceed the Maturity Date of the Mortgage. The Fixed interest rate will be based on the current rates for Reading Cooperative Bank’s Fixed Rate Home Equity Loan product at the time the Conversion Election Option is executed. Please ask about our current rates. The availability of this Conversion Option will terminate at the end of the Draw Period. Each “Fixed Rate, Fixed Term Option” Addendum will be secured by, and be subject to, the terms and conditions of the existing home Equity Line of Credit Agreement and Disclosure Statement.

Minimum Payment Requirements – You can obtain advances of credit for 10 years (the “draw period”). During the draw period, payments will be due monthly. Your minimum monthly payment will equal all accrued interest as of the closing date of the billing cycle, plus any amounts past due.

Interest Only Payments – Your minimum monthly payment during the draw period will not reduce the amount of principal outstanding on this line of credit.

After the draw period ends, you will no longer be able to obtain credit advances and must pay the outstanding balance over 15 years (the “repayment period”). During the repayment period, payments will be due monthly. Your minimum monthly payment will equal 1/180th of the principal balance that was outstanding at the end of the draw period plus the interest that has accrued on the remaining balance. During the repayment period the annual percentage rate will continue to adjust monthly.

Discounted Fixed Rate Home Equity Loans (Loans up to $300,000)4,5,6*Requires Autopay Enrollment*
  
TermRateAPR3Payment Per $100,000
10 Year5.990%6.032%$1,109.70
15 Year6.240%6.273%$856.88
20 Year6.490%6.520%$744.98

1For loan amounts up to $250,000, your debt-to-income ratio cannot exceed 45%, and you will need a minimum mid Fico Score of 620. CLTV cannot exceed 75%.
2Depending on your loan to value, debit to income ratio, and credit score, you may qualify for a higher loan amount. Please speak to a loan officer for more details.
3APR (Annual Percentage Rate) – is the annual rate that is charged for borrowing, expressed as a single percentage number that represents the actual yearly costs of funds over the term of the loan. This includes any fees or additional costs associated with the transaction. Minimum payment does not include insurance and taxes, and the payment may be greater.
4This discount only applies to residential owner-occupied properties and customers who have enrolled in Autopay.
5Minimum loan amount is $50,000. Maximum loan amount is $300,000. Minimum FICO score 680. DTI cannot exceed 45%. Maximum LTV of 80%. Borrower must have or open an RCB deposit account with automatic payments to the loan. Rates reflect discount for automated payments from a qualified RCB deposit account.
6Any loan exceeding $250,000 will require a full appraisal. Drive-by appraisal (LSI Limited Appraisal/Summary Report) for loans up to $250,000.

Fixed Rate Home Equity Loan rates and terms are effective as of 06/10/2026 and are subject to change at any time without notice. Discounted Fixed Rate Home Equity Loan rates are effective as of 06/10/2026.

RCB Dots Shape